Spain’s Sánchez Proposes Bank Tax Extension to Raise €1.4 Billion for Housing
The Spanish prime minister wants to keep the banking levy in place through 2027, with projected receipts directed to protected homes, tenant relief and renovation.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy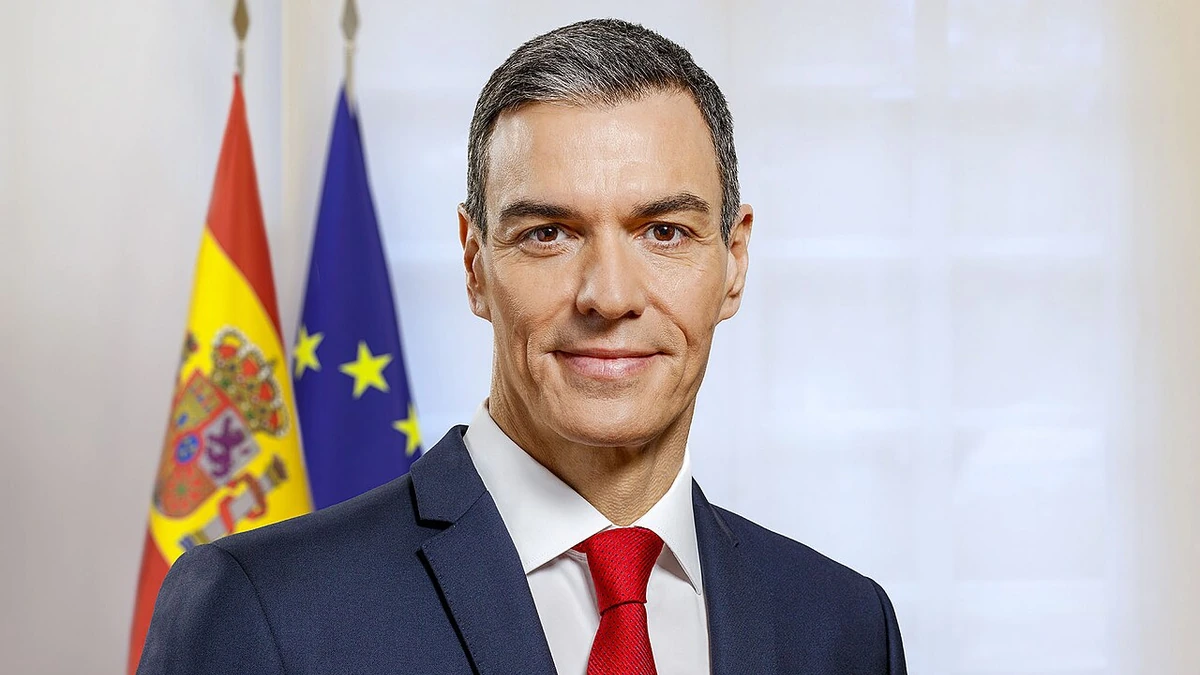
Spanish Prime Minister Pedro Sánchez has proposed extending the country’s tax on banks through 2027 and directing an estimated €1.4 billion in proceeds to housing policies, adding a funding pledge to a contentious issue ahead of Spain’s general election. The government intends to approve the extension at a cabinet meeting on Tuesday, November 24, according to Sánchez’s announcement on Saturday.
The money would be used for protected housing, tax relief for tenants and the renovation of existing homes. The €1.4 billion figure is the government’s expected collection under the proposed extension, not cash already received or a housing appropriation that has been enacted.
Sánchez outlined the plan during an interview with Onda Cero. His Socialist Party subsequently confirmed the proposed extension and the intention to use the expected receipts for housing. As of Saturday, the detailed text of the new measure had not been presented in the sources reviewed.
Three housing priorities, but no detailed allocation
The proposal identifies three uses for the money without specifying how much each would receive. Constructing protected homes would address the supply of below-market or publicly supported housing. Tenant tax concessions would instead operate through the tax system, and rehabilitation would aim to improve or return existing properties to usable condition.
Those distinctions matter for assessing the €1.4 billion promise. A euro committed to building a home is different from a euro of tax relief to a renter, and the timing of either benefit depends on program rules. The announcement did not specify a number of homes to be built, an eligibility test for tenant relief or the financial split between construction, tax measures and refurbishment.
It is also not yet clear from the announcement whether the projected tax receipts would be legally reserved for these purposes, allocated through existing budgets or accompanied by separate spending legislation. Until the cabinet publishes the measure, the proposed funding should not be described as an approved new €1.4 billion housing program.
The emphasis on housing reflects pressure on Spain’s property market. In its October economic projections, the Bank of Spain said new residential construction had failed to keep pace with household creation, contributing to rising real house prices. The central bank also identified labor shortages, slow urban development and scarcity of land ready for construction as constraints on supply.
Those obstacles mean additional public financing would not necessarily turn into completed homes quickly. The central bank expected housing investment to increase but warned that its pace would still depend on the ability of developers and public programs to overcome structural restrictions. This makes the mix between building projects and more immediate tenant support consequential, even if the total tax estimate is achieved.
What the existing banking tax actually charges
The proposal would prolong an existing levy rather than introduce an entirely new charge on banks. Under Spain’s Law 7/2024, the tax applies to the positive margin earned from interest and commissions tied to financial activity in Spain. It is not simply a flat percentage of a bank’s reported net profit.
The law covers Spanish credit institutions, certain financial credit establishments and Spanish branches of foreign credit institutions. The taxable base is calculated from net interest and commission items, with the first €100 million deducted before the rate schedule is applied. The rates are progressive, starting at 1% and rising through several brackets to 7% on the highest band.
The headline rates do not, by themselves, determine the amount a bank ultimately pays. The legislation includes a reduction linked to corporate income tax and additional relief tied to profitability as measured against assets. The government has not released, in the material reviewed, a bank-by-bank calculation supporting the new €1.4 billion projection.
The current statutory framework applies to the first three consecutive tax periods beginning in 2024, which for banks using calendar-year accounting covers 2024 through 2026. Extending it into 2027 therefore requires a new legal step. It would preserve a recurring source of public revenue for at least another year if adopted, but the amount collected will depend on the eventual rules and banks’ taxable margins.
The taxation of margins and commissions also makes the revenue estimate sensitive to changes in banks’ business conditions. Interest-rate movements can alter the difference between what lenders earn on loans and pay on funding, while fee income, operating costs and statutory deductions affect the calculations. A government projection should not be read as a guaranteed sum available at the start of the year.
Existing regional revenue rules raise an implementation question
One part of the current law is particularly important to the housing pledge. The enacted banking-tax framework provides for revenue to be distributed to Spain’s common-regime autonomous communities, using a formula based on regional gross domestic product and a specified timetable. That is different from directly reserving all proceeds for three nationwide housing initiatives.
The distinction does not make Sánchez’s plan impossible, but it creates a question that the cabinet text will need to answer: how the proposed extension would connect bank-tax receipts to the announced housing purposes, and whether existing distribution rules would change. The announcement itself is not evidence that the present allocation provisions have already been amended.
Regional and local authorities also have practical roles in delivering housing. Planning permissions, land availability and local construction capacity can shape the timing of projects regardless of how money is raised. The Bank of Spain’s latest projections specifically pointed to bottlenecks in urban development and labor as reasons the response to stronger housing demand has remained limited.
The extension has an immediate political setting. Sánchez made the announcement during the campaign for the November 29 general election and indicated that his government would take the proposal to cabinet before polling day. An executive announcement and cabinet approval are not the same as a fully enacted tax extension; the legal instrument and any further required legislative steps must be assessed once the text is public.
Tuesday’s cabinet meeting is therefore the next concrete test of the proposal. The documents published afterward should clarify the tax’s proposed duration, how the €1.4 billion revenue forecast was derived and, most importantly for housing policy, the mechanism by which the money would be directed to construction, renter relief and rehabilitation.
More from Banking
Latest News
View all news- Washington’s Updated Gold and Silver Bullion Tax Rules Take Effect
- India’s Exports to Africa Jump 44%, Asia Shipments Rise 21%, Government Data Shows
- Six One Commodities’ U.S.-Canada Gas Trading Authorization Begins Two-Year Term
- Canada Announces C$248,063 Investment to Restore Nova Scotia Lighthouse and Support Tourism
- New York’s New CPA Licensing Law Takes Effect, Adding 120-Credit Pathway