
Bank of England’s Ruth Smith Sets Out ‘No Bank Too Big to Fail’ Resolution Case
Ruth Smith said the Bank of England is reviewing where smaller banks should move from insolvency to transfer strategies, with an updated approach expected in early 2027.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy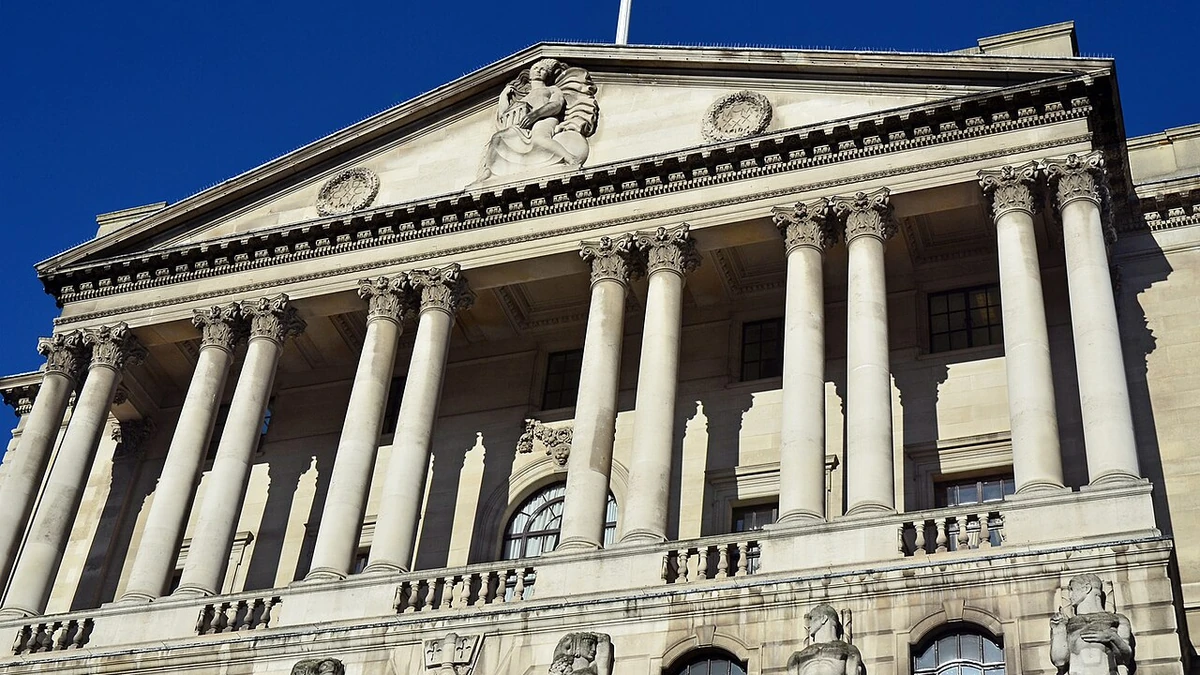
Bank of England resolution chief Ruth Smith has set out why the UK’s post-crisis promise that no bank should be “too big to fail” now has to be matched by credible plans for smaller firms whose collapse could still disrupt customers or confidence in the financial system.
Speaking at the Florence School of Banking and Finance on September 23, Smith said the UK framework deliberately uses different resolution strategies for different types of banks, but size is not the only consideration. The practical question is whether an institution can be wound up without unacceptable disruption, or whether authorities need to preserve banking services through a transfer or, for the largest firms, a bail-in.
In her speech at the European University Institute in Florence, Smith focused on the boundary between insolvency and transfer for small and medium-sized banks. That boundary has become more important since the 2023 failure of Silicon Valley Bank UK and subsequent changes to the UK resolution regime.
Resolution strategy now turns on more than bank size
The Bank broadly plans around three groups. The largest and most complex banks are generally expected to be resolved through bail-in, which can impose losses on shareholders and eligible creditors and convert loss-absorbing resources into equity so the bank can be recapitalised and restructured. These firms are required to maintain minimum requirements for own funds and eligible liabilities, known as MREL, above ordinary minimum capital requirements where the Bank considers those resources necessary for the resolution strategy.
For banks with roughly £25 billion to £40 billion of total assets, the Bank can choose between a transfer strategy and bail-in on a firm-specific basis. A transfer can involve selling the bank, or part of it, to a private-sector purchaser. If a buyer is not immediately available, the Bank can also use a temporary bridge bank while it works toward a sale.
Smaller banks, generally those with less than £25 billion of total assets, are more likely to have modified insolvency as their preferred strategy. Under the Bank Insolvency Procedure, the Financial Services Compensation Scheme can protect eligible depositors through payout or a transfer of covered deposits while the rest of the failed institution is wound up. Smaller firms are not automatically pushed into insolvency, however. The Bank can set a transfer strategy where it judges that insolvency would not meet the statutory resolution objectives.
That judgment already looks beyond the balance sheet. The Bank’s current MREL policy uses a range of 40,000 to 80,000 transactional accounts as an indicative point for considering whether a sub-£25 billion institution provides enough day-to-day banking services that a transfer may be more appropriate. It is not a hard threshold. The nature of the business, the services customers depend on and the potential effect on financial stability also matter.
The framework has also become less costly for some firms to maintain in normal times. Transfer firms are no longer expected to hold MREL above minimum capital requirements. The policy change reflects the Bank’s effort to keep resolution planning proportionate while retaining a credible way to preserve critical services if a smaller institution fails.
SVB UK made the boundary problem concrete
Silicon Valley Bank UK is the clearest recent example of why a preferred resolution strategy cannot be treated as an automatic outcome. At the time of its failure in March 2023, SVB UK had a balance sheet of about £12 billion and fewer than 40,000 transactional accounts, which put it within the profile of a firm expected to enter modified insolvency.
On Friday, March 10, the Bank said it intended to place SVB UK into a Bank Insolvency Procedure if no meaningful new information emerged. Over the weekend, prospective buyers came forward and HSBC became a credible purchaser. By Monday morning, the Bank had transferred SVB UK to HSBC after concluding that a sale would better protect depositors, maintain continuity of banking services and support confidence in the UK financial system.
The Bank’s later report on the resolution said the transfer kept all deposits safe and accessible and required no use of UK public funds. The episode also showed how quickly a smaller bank’s resolution profile can change when authorities learn more about its customers, its role in payments and the wider market backdrop. A bank can be small by assets but still serve customers for whom even a short interruption in access to accounts or payments would be consequential.
Smith’s argument is therefore less about replacing insolvency than about preserving options. The Bank still regards modified insolvency as a credible and proportionate route for many smaller firms. The lesson from SVB UK is that authorities need the operational readiness to switch to a transfer when the public-interest assessment changes during a fast-moving failure.
An industry-funded mechanism widens the Bank’s options
The biggest policy addition since the SVB UK failure is the recapitalisation payment mechanism created by the Bank Resolution (Recapitalisation) Act 2025. The mechanism allows the Bank, when exercising transfer powers, to require the FSCS to provide funds that can help recapitalise a failing bank or support its transfer to a private purchaser or bridge bank.
The costs are designed to be recovered from the banking sector through FSCS levies rather than treated as a routine taxpayer bailout. Bank guidance says regulatory capital would be written down first, and available MREL resources would also be exposed to loss before the recapitalisation mechanism is used. The amount required would depend on the resolution valuation and the specific costs needed to make a transfer workable.
The mechanism can address a practical problem that often appears in a weekend resolution: a buyer may have very little time to conduct due diligence and may be unwilling to take on an uncertain capital shortfall or other risks. The Bank’s transfer guide says recapitalisation funds could be used for an upfront capital injection or, in some cases, a contingent or deferred payment such as a guarantee. Those options are intended to make an orderly transfer more feasible without requiring every smaller bank to pre-fund the same level of loss-absorbing resources as a large bail-in firm.
There are limits. The mechanism is tied to the use of transfer powers and is not meant to insulate shareholders or creditors from losses that should otherwise fall on them. The Bank also has to consider the public interest and the wider cost to the industry, because banks and building societies can ultimately be levied to recover the FSCS outlay. HM Treasury retains responsibility for any use of public funds, which remains a separate last-resort consideration in the broader resolution framework.
Smith said the Bank is now reviewing the existing 40,000 to 80,000 transactional-account indicator for smaller banks. Consumer banking behaviour has changed since that measure was introduced, and the new recapitalisation mechanism gives the Bank more flexibility to transfer a firm that does not hold additional MREL. The review is also looking at whether existing supervisory, recovery and solvent-exit data can give authorities better information before a bank reaches the point of failure.
The next concrete step is an updated Bank of England approach expected in early 2027. That work will determine how the UK draws the line between insolvency and transfer for smaller institutions after SVB UK and after the addition of the industry-funded safety net. It is the part of the resolution regime most directly tied to Smith’s broader case: ending “too big to fail” is not enough if authorities are unprepared for a smaller bank whose failure turns out to matter more than its balance sheet suggests.
More from Banking
Latest News
View all news