Norway Regulator Details Mortgage and Governance Gaps at DNB, Sparebanken Norge
Finanstilsynet’s new supervision reports call for changes to DNB’s retail mortgage assessments and further governance and risk-management improvements at Sparebanken Norge.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy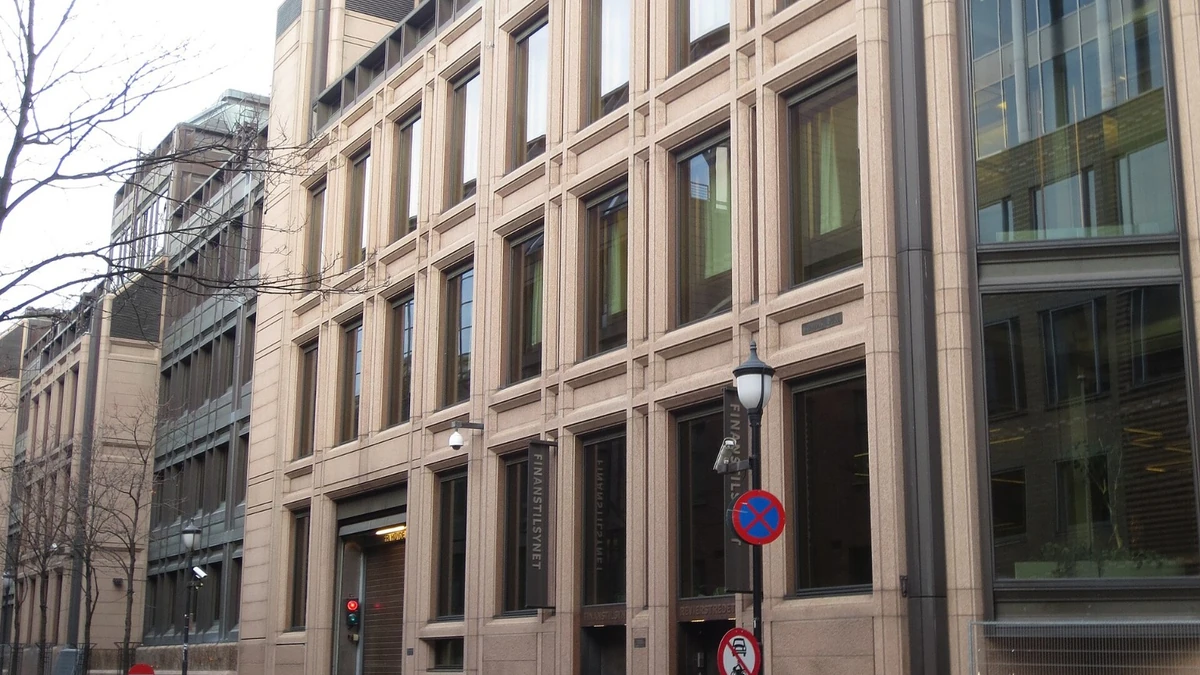
Norway’s financial regulator published new supervision reports on DNB Bank ASA and Sparebanken Norge on September 23, setting out separate concerns at two of the country’s largest banking institutions. The DNB review focused on credit risk, governance and control, and consumer protection in the personal banking business, with particular attention to residential mortgages. The Sparebanken Norge review examined the banking group’s system for internal governance and risk management.
The reports are supervisory assessments rather than enforcement decisions. Finanstilsynet’s latest-report portal classifies both cases as “Ingen reaksjon,” or no reaction, so the regulator published findings and expectations without an accompanying formal sanction or administrative decision.
The two reports appear together among the regulator’s latest publications in Finanstilsynet’s supervision portal. They cover different risk areas, but both center on whether internal processes give management and boards a sufficiently reliable view of risk and whether controls are working as intended.
DNB mortgage review centers on affordability calculations
Finanstilsynet’s DNB review covered the bank’s personal banking division, which is its largest business area. Norwegian reporting that cites the newly published report says the onsite review was carried out in December 2025 and examined the bank’s mortgage credit practices, its management of credit risk, and consumer-protection controls.
The most concrete issue concerns how DNB assessed whether mortgage customers could afford their debt under higher interest rates. E24 and Finansavisen, citing the regulator’s report, said Finanstilsynet found examples in which relevant expenses were left out or income was overstated in affordability calculations. The regulator also objected to DNB’s use of a standardized mortgage interest rate as the starting point for stress testing rather than the rate actually offered to the customer.
Finanstilsynet’s current consumer-lending guidance requires banks to assess repayment capacity using the customer’s income and all relevant expenses, including interest, loan repayments and ordinary living costs. It also says the calculation must include a three-percentage-point increase in the interest rate on the customer’s total debt, with a minimum assumed rate of 7%. The new DNB report, as described in contemporaneous coverage, focuses on the rate from which that stress is calculated and says the bank should use the rate offered to the individual customer.
DNB has indicated that changing the approach will require substantial system work and that the changes will be incorporated into modernized credit processes, according to accounts of the published report. Finanstilsynet also signaled that it will follow the interest-rate testing issue in a separate matter. The bank has been asked to provide a status report as of March 31, 2027.
The review goes beyond the mortgage stress-test calculation. It also points to improvements in the governance and control of operational risk, further development of risk reporting, and refinements in procedures for customer complaints, borrowers experiencing payment problems and debt enforcement. E24 reported that DNB’s personal banking exposure totaled NOK 1.073 trillion, of which NOK 1.007 trillion was in residential mortgages, underscoring the scale of the business covered by the review.
Sparebanken Norge is told to strengthen parts of its governance framework
The Sparebanken Norge report takes a broader governance view. Finanstilsynet’s overall assessment is that the bank has established governing bodies, frameworks and processes suited to its activities, but the regulator also identified several areas where it expects stronger arrangements.
One of the clearest observations concerns the chief financial officer’s span of responsibility. E24, citing the report, said Finanstilsynet considers the CFO’s responsibilities to create a large and demanding control span across both day-to-day operations and risk control. The regulator also said the bank should strengthen the resources available to internal audit.
Scenario analysis and stress testing are another focus. The report calls for stronger work in those areas to provide a better view of future risk, according to the same account. Finanstilsynet also wants the bank’s risk-appetite framework to cover a broader set of risks, including business risk, profitability and capital adequacy. The bank’s board agrees with the supervisory assessments and has started measures to address the points raised, E24 reported.
The governance review comes relatively soon after a major change in the bank’s structure. Sparebanken Norge was created on May 2, 2025 through the merger of Sparebanken Vest and Sparebanken Sør. The bank says it is an independent listed financial group with headquarters in Bergen and Kristiansand and 68 local offices. That history does not establish the cause of any finding in the supervision report, but it provides context for the regulator’s close attention to governance responsibilities, internal audit capacity and group-level risk processes.
Both banks remain under heightened systemic oversight
DNB and Sparebanken Norge also sit inside Norway’s group of systemically important financial institutions. The Ministry of Finance said on September 21 that DNB, Sparebanken Norge and three other institutions are to continue being treated as systemically important. DNB is subject to a 2% systemic-importance buffer, while Sparebanken Norge is due to meet a 1% buffer requirement from March 31, 2027, according to the ministry’s latest notification.
The systemic designation is separate from the September 23 supervision reports. It does, however, help explain the intensity of supervisory attention to governance, credit underwriting and risk controls at these banks. A weakness in mortgage affordability testing at DNB concerns a very large retail loan book, while governance weaknesses at Sparebanken Norge are being assessed at an institution that has grown into one of the country’s systemically important banks.
Neither September 23 report is presented in Finanstilsynet’s portal as a formal reaction. For DNB, the clearest dated follow-up is the requested status report for March 31, 2027, alongside the regulator’s separate follow-up of the mortgage stress-testing issue. Sparebanken Norge has already indicated through its board response that remedial work is under way on the governance and risk-management points identified by the supervisor.
More from Banking
Latest News
View all news