
UK Economy Grows 0.1% in August, With Three-Month GDP Growth Reaching 0.7%
Factory output lifted August GDP despite flat services and weaker construction, while professional and technology-related services sustained growth over the three-month period.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy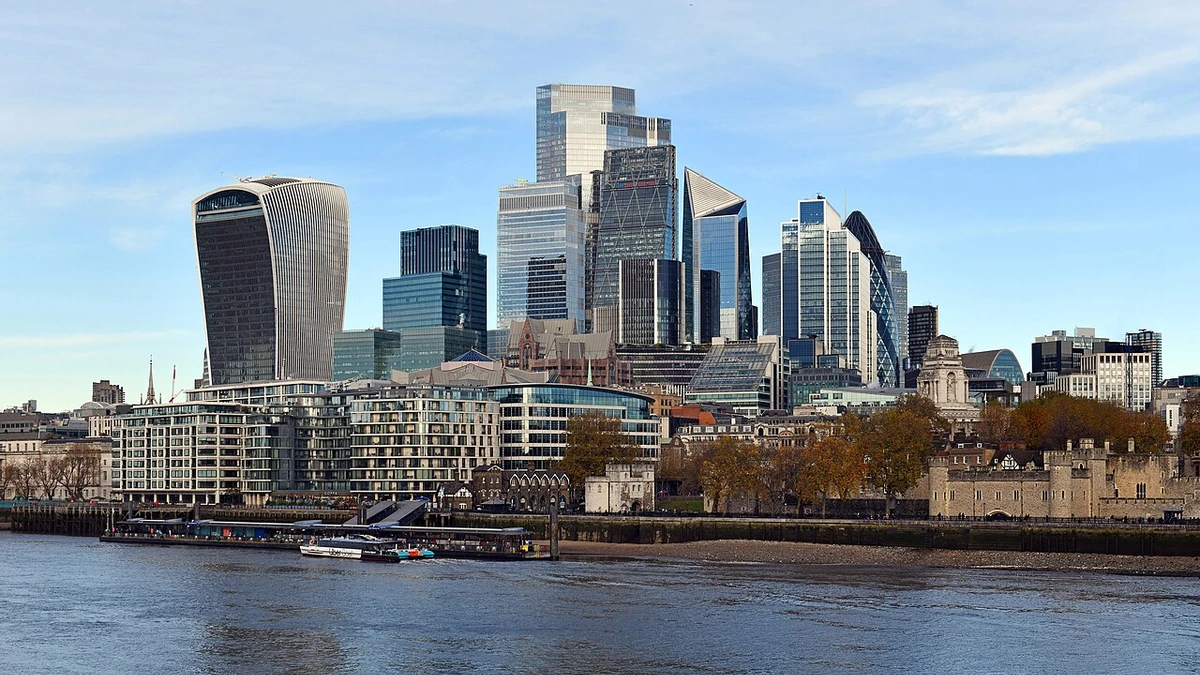
The UK economy grew by 0.1% in August 2026, slowing from July even as a stronger run of growth in business services lifted output over the latest three-month period. Gross domestic product rose 0.7% in the three months to August, according to figures released Thursday by the Office for National Statistics (ONS).
The two readings describe different parts of the economy’s performance. August’s modest gain came mainly from factories and other production industries, while the larger three-month increase reflected sustained strength in services. Construction contracted on both measures, and consumer-facing businesses had a weaker August than the headline GDP figure suggests.
In its August GDP release, the ONS reported a 0.8% monthly rise in production output, no growth in services and a 0.2% decline in construction. July’s 0.4% increase in GDP was unchanged, while June’s growth was revised up to 0.4% from 0.3%. Those revisions help explain why the three-month picture looks firmer than the latest single month.
Manufacturing supplies the monthly boost
Manufacturing output increased 1.2% in August after rising 1.0% in July, with nine of its 13 subsectors recording gains. Pharmaceutical manufacturing was the largest positive contributor, growing 5.1% on the month. Transport-equipment production increased 1.8%, although it followed a decline in July. These gains were not universal: other manufacturing and repair fell 2.1%, and production of food, beverages and tobacco declined 1.0%.
The broader production sector grew 0.8%, also supported by a 1.4% rise in mining and quarrying. Water supply, sewerage, waste management and remediation activity fell 1.2%. The monthly rebound therefore offered a lift to GDP without establishing that industrial output had strengthened consistently across the summer.
Services, which account for the largest share of the UK economy, were flat in August after increases of 0.5% in each of June and July. Only four of the 14 services subsectors expanded that month. Wholesale and retail trade, including motor-vehicle repair, rose 2.0%, helped by a 3.8% increase in wholesale trade excluding motor vehicles. That wholesale category had previously fallen for five consecutive months and remained 1.6% below its February level.
Professional, scientific and technical activities also advanced, rising 1.5% in August. Legal services increased 3.3%, and architectural, engineering and technical-testing activities gained 2.0%. The gains were countered in part by a 1.7% fall in administrative and support services, including weaker rental and leasing activity. A flat overall services figure concealed sizeable movements in both directions.
Business services lead growth over three months
The rolling three-month GDP measure rose 0.7% compared with the preceding three months. That followed growth of 0.5% in the three months to July, a figure revised up from the previously reported 0.4%. The ONS recorded an eighth consecutive increase on this rolling basis. Because the periods overlap, the three-month measure smooths out monthly changes rather than representing a separate full calendar quarter.
Services output increased 0.9% in the three months to August and was the only one of the three main sectors to contribute positively to GDP growth over that period. Ten of the 14 services subsectors expanded. Professional, scientific and technical activities and information and communication each grew 2.8%, making them central to the stronger underlying reading.
Within information and communication, computer programming, consultancy and related activities grew 5.0% over the three months. The ONS identified that industry as the largest contributor to three-month growth for a sixth consecutive month. Scientific research and development grew 4.9%, while legal activities increased 3.4%. Those are measured increases in industry output; the figures do not, by themselves, establish how much of the growth came from any particular technology or investment trend.
Elsewhere, the expansion was uneven. Wholesale trade excluding motor vehicles fell 2.3% across the three months despite its August recovery. Production output declined 0.2% on the same rolling basis, and manufacturing managed growth of only 0.1%. That contrast shows why the August factory gain should not be mistaken for an equally strong industrial performance over the whole period.
Compared with August 2025, GDP in August was 2.1% above its level a year earlier, the highest such monthly annual growth rate since August 2022, according to the ONS. Output in the three months to August was 1.8% higher than in the same period of 2025, with professional services and information and communication making particularly large contributions.
Consumers and construction show a weaker side
Consumer-facing services contracted 0.3% in August, following a revised 0.1% decline in July. Sports, amusement and recreation activities fell 7.1%, and food and beverage service activities were down 2.7%. Motor-vehicle sales and repair activity provided some offset, growing 2.7%. These categories are a narrower measure than all household spending, but they show that the economy’s monthly growth was not evenly reflected in businesses serving consumers directly.
Across the three months to August, consumer-facing services increased 0.4%. Accommodation output rose 2.8%, and retail trade excluding motor vehicles gained 1.1%, but food and beverage services fell 1.5%. The difference between the monthly and rolling figures suggests recent softness within an otherwise slightly positive three-month period.
Construction output fell 0.2% in August, its fourth consecutive monthly decline. July is now estimated to have fallen 0.5%, a substantial downward revision from the previously reported 0.1% increase. New construction work decreased 0.7% in August, with private housing new work down 1.9%, whereas repair and maintenance grew 0.4%. Over three months, construction output fell 1.0%, including a 3.2% decline in private housing new work.
Early indicators suggest pressure continued in September, although they are not GDP data. In real-time figures cited by the ONS, wholesale electricity and gas prices remained more than twice their year-earlier levels. September retail footfall was slightly lower than a year earlier, and new housing sales listings remained below their previous-year level. These indicators provide context, not a confirmed estimate of output in September.
Revisions and the next GDP release
The latest report incorporates updated historical figures consistent with the ONS’s Blue Book 2026 revisions and its September quarterly national accounts. In those accounts, GDP growth for April to June 2026 was revised up to 0.5% from 0.4%, following growth of 0.6% in the first quarter. This month’s GDP estimates rely on the output measure, whereas the quarterly national accounts draw on output, income and spending data.
The 0.7% increase for the three months to August is not the official growth rate for the July-to-September calendar quarter. September’s output is still missing from that calculation, and early monthly estimates can be revised as more business responses arrive. The distinction matters when comparing the rolling indicator with the UK’s published quarterly GDP performance.
The ONS is scheduled to publish September retail sales figures on October 23 and its next monthly GDP estimate on November 12. That November release, alongside the next quarterly GDP figures, will give a fuller view of whether August’s slow monthly pace carried into the end of the third quarter.
More News
Latest News
View all news- Union Pacific Third-Quarter Profit Rises 16% to $2.1 Billion as Freight Volumes Grow
- Nasdaq Q3 Revenue Jumps 13% as Annual Recurring Revenue Reaches $3.4 Billion
- Census Bureau Releases New Business Conditions Data Covering U.S. Employers
- Blackstone Reports Third-Quarter Earnings With Assets Under Management Near $1.4 Trillion
- BEA Expands State-Level R&D Economic Statistics With New 2024 Estimates
