
U.S. Construction Spending Falls 1.9% in September as Residential Building Outlays Slide
Private residential outlays fell 5.5% as spending on nonresidential projects rose, leaving overall September construction activity below its year-earlier level.
Our editorial standards
MarketReview publishes clear, independently produced financial information using reliable sources and transparent editorial standards.
Read our Editorial Policy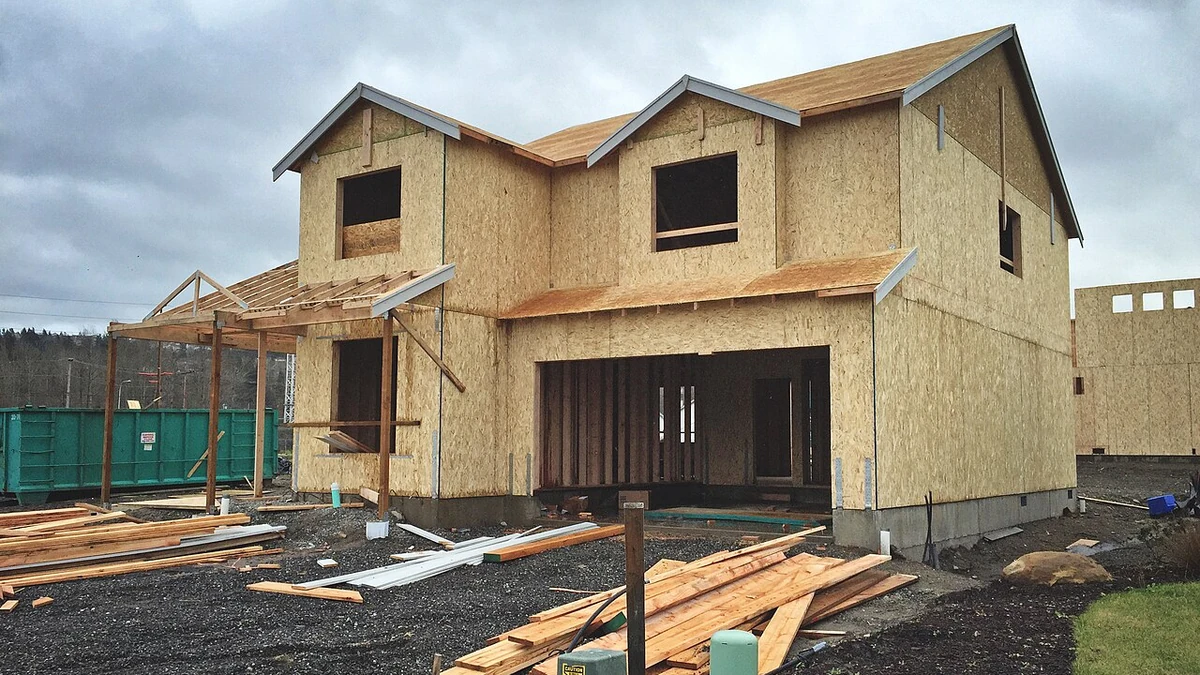
U.S. construction spending fell 1.9% in September to a seasonally adjusted annual rate of $2.1861 trillion, reversing much of the previous month’s upwardly revised increase. The largest weakness came from private residential construction, where outlays declined 5.5% even as spending on private nonresidential projects increased.
The September decrease followed a revised 2.0% rise in August, compared with the 0.9% gain first reported for that month. Spending was also 2.7% below its September 2025 level. Those figures point to a sharp monthly setback, but the revision to August is a reminder that the latest estimates can change as more project information becomes available.
The figures come from the U.S. Census Bureau’s monthly construction-spending program, which measures the dollar value of work put in place on projects across the country. The estimates cover both private and public construction and are expressed at annualized rates after seasonal adjustment. They are not adjusted for changes in construction prices.
Residential outlays account for the biggest weakness
Private construction spending dropped 2.4% in September after rising 2.6% in August. The residential component fell considerably faster than private construction overall, making housing-related work the clearest source of the month’s weakness. That was a marked contrast with the 1.1% increase in private nonresidential spending.
The details within residential construction were less uniformly negative. Spending on new single-family homes was unchanged from August, although it was 2.4% lower than a year earlier. Multifamily construction outlays edged up 0.1% on the month. Those comparatively steady readings for new homes sit alongside the 5.5% fall in the broader residential category.
One reason the figures can diverge is that residential spending includes improvements to existing homes as well as new single-family and multifamily construction. A drop in the overall category therefore should not be interpreted as a 5.5% decline in spending on newly built houses alone. The published monthly changes indicate that work outside the two new-building categories was an important part of the picture, but they do not by themselves establish why homeowners or contractors reduced spending.
Other housing indicators also pointed to a restrained market in September, though they measure different stages of activity. In its October 20 report, the Census Bureau said housing starts fell 5.2% to an annual pace of 1.221 million units. Single-family starts declined 4.6% to 859,000 units, while building permits for all privately owned housing were down 0.2% at 1.4 million units. The bureau’s reported confidence intervals mean the monthly changes in total and single-family starts were not statistically distinguishable from zero.
A housing start records the beginning of work on a new unit; construction spending captures the value of work performed on projects at different stages of completion. The two series can move in different directions over a short period. September’s spending figures are consequently more informative about the immediate flow of construction work than about how many homes builders may complete or sell later.
Nonresidential work offers a contrast
Private nonresidential construction spending increased 1.1% in September, providing a partial offset to the decline in residential work. Spending on power projects rose 1.2%, and office-related outlays increased 5.5%, according to the reported breakdown. The gains did not prevent an overall pullback in private construction because the residential decrease was much larger.
The office category is broader than conventional office buildings and can include data-center construction, so its monthly increase should not be read as evidence of a recovery in traditional office development. Nor does the power-project gain establish that investment is strengthening across all industrial or infrastructure categories. The data show which classifications expanded in September, not a uniform improvement in business construction.
Public construction spending was little changed, declining 0.1% after an August increase of 0.2%. Within that total, state and local government project outlays decreased 0.3%, while federal construction spending rose 2.5%. These opposing movements help explain why the overall public figure was relatively stable despite the sharper contraction in the private sector.
The split matters because private housing work, commercial projects and publicly financed construction depend on different decisions and funding schedules. A decline in the headline figure does not mean contractors across every category experienced the same conditions. September’s composition instead shows weakness concentrated in one large part of private activity, alongside areas that continued to record growth.
Revisions and price changes limit what the monthly decline shows
The upward revision to August is particularly important when interpreting September. August was initially reported as a 0.9% increase, but the latest accounting put the gain at 2.0%. September’s 1.9% fall therefore largely unwound the revised advance rather than following an uninterrupted run of monthly declines. Looking only at the original August estimate would give a misleading impression of the month-to-month sequence.
The year-over-year decline of 2.7% provides a different comparison, but it is still measured in current dollars. Changes in material prices, labor costs and the mix of projects can affect nominal spending independently of the physical amount of construction completed. The reported decline is not, by itself, a measure of a 2.7% reduction in inflation-adjusted construction output.
Census estimates also carry sampling uncertainty and may be revised in subsequent releases. The agency cautions that monthly movements can be irregular, especially in narrower project categories. A single month’s sharp decline is therefore useful evidence of weaker reported spending, but it cannot establish the persistence of a trend or identify a definitive cause without further data.
The next scheduled construction-spending report, covering October, is due December 1. It will provide another reading on whether residential outlays stabilized after September’s drop and may revise the latest estimates for earlier months.
More News
Latest News
View all news- Westpac Reports A$6.8 Billion Annual Profit, Declares 77-Cent Final Dividend
- SEC Opens Consultation on $100 Billion Alternative Compliance Cap for Security-Based Swap Dealers
- OCC and FDIC’s Revised Standards for Unsafe Banking Practices Take Effect
- Marvell to Acquire Lumentum in $115 Billion All-Stock Deal to Expand AI Connectivity Business
- U.S. Proposes Zero Dumping Margins for Two South Korean Power Transformer Manufacturers
